5.0
Based on 3 reviews

Fast Secured Finance

Secured Loan Calculator

Work out how much you could borrow against your asset in seconds, then request a free valuation to confirm your loan offer.

  1. 1Calculate your loan
  2. 2Get a free valuation
  3. 3Receive your funds

Step 1 · Estimate your loan

Max Loan Amount: £0
Est. Monthly Interest: £0

*Maximum loan amount is capped at £250,000.
*Standard loan interest is 5%, but lowered for larger loan amounts.

Free, confidential and we’ll get back to you the same day.

Step 2 · Get your free valuation

Free Asset Valuation

Select your asset type to get an instant provisional loan offer.

Final Details

100% Confidential. No credit footprint left.

Request Received
Our specialized valuation team is reviewing your asset and will call you the same day.
  • Loans from £150 to £250k+ available
  • 7-month contracts with flexible repayment options (no monthly repayments required)
  • Fast secured loan valuations and decisions, often made the same day, ensure you can secure your loan offer quickly.
  • Applying for a secured loan with us is fast and easy. Fill out our form or contact us and we'll get back to you the same day.

Fast Legal Completion

100% Discreet Lending

FCA Regulated

How to Apply For a Secured Loan

We remove the red tape. Our streamlined underwriting process ensures you get the funds you need without the high-street delays.

1. Fast Secured Loan Valuation

Contact us with your asset details to receive your personalized loan offer. We arrange a rapid valuation based on current market prices, very often on the very same day (you can also apply for your loan online), to accurately assess the value of your asset.

2. Secure Storage & Agreement

Once valued, your loan is secured against your asset (physical items are kept in our secure vault), and we swiftly prepare your 7-month loan agreement.

3. Funds Released

Once documents are signed, funds for your secured loan amount are immediately transferred to your account or cash in person. There are no monthly payments required, and you can redeem the loan at any time with no exit fees.

Client Success

Trusted by Investors & Secured Loan Clients
LoanAgainstAssets place picture
5.0
Based on 3 reviews
Anong Sawan profile picture
Anong Sawan
2 months ago
Very easy to deal with, I bad credit but they loan against silver bar and gold bar I have but want to keep. Happy I needed the money to help the Bill's whilst business is slow. Thank you
Al K profile picture
Al K
3 months ago
Saved my mum's house move. We were about to lose the property she wanted to move to because our buyer was dragging their heels. The property bridging loan the team gave us was reasonable and quick, which allowed us to complete on the property we wanted to buy before we lost it waiting for the buyer of our property to sort themselves out. Forever grateful!
Wayne Renold Reid profile picture
Wayne Renold Reid
7 months ago
Used this company for a short term loan, % was reasonable, very straight forward, explained everything clearly. No credit checks either. Would use again.

Secured Loan FAQs

Clear answers to common questions about our secured loans, grouped by the type of asset you borrow against.

FAQ's About Loans Against Property and Land

Answers regarding our loans against property and loans against land.

A home loan or mortgage is normally used to purchase a property and is based heavily on income, affordability and credit history. A loan against property uses property or land you already own as security. At Loan Against Assets.co.uk, our main consideration is the value and ownership of the asset being offered.

No. You remain the owner of the property. Security may be registered against the title for the duration of the loan. Once the loan and agreed charges have been repaid, that security is removed.

Yes. LoanAgainstAssets.co.uk can consider commercial property, residential property, buy-to-let property, garages, development sites and empty plots of land. We primarily check the Land Registry title, ownership, existing charges and current value of the asset. A conventional credit score is not usually the deciding factor.

Yes. We can consider applications from self-employed people, company directors, property investors and business owners. Our lending is based primarily on the property or land being offered as security, rather than requiring the same employment history and payslips as a high-street bank.

Please contact us immediately if you expect to miss a payment. We will explain the amount outstanding and discuss the available options. The property is not taken after one late payment. However, because the loan is secured, continued default beyond the loan term could eventually result in enforcement and sale of the property. This would only happen in accordance with the loan agreement and the applicable legal process.

The money received from a loan is not normally treated as taxable income. Whether the interest or fees can be claimed as a business expense depends on how the money is used and the borrower’s circumstances. Loan Against Assets.co.uk does not provide tax advice, so you should speak to an accountant if the loan is being used for business or investment purposes.

The main factors are the property type, location, value, loan amount, existing mortgages or charges and the complexity of the Land Registry title. Legal work, searches and an independent valuation may also be required. All applicable charges will be explained before the loan is completed.

We do not assess an application solely on age. The main considerations are ownership, asset value and how the loan will be repaid. Each application is considered individually.

Potentially, yes. Loan Against Assets.co.uk specialises in asset-backed lending, so the value of the property and the proposed repayment plan are more important than conventional payslips. We will still need to understand how the loan will be repaid and complete the necessary identity, ownership and compliance checks.

FAQ's About Loans Against Gold and Jewellery

Answers regarding our loans against gold and loans against jewellery.

There is no single percentage that applies to every item. Loan Against Assets.co.uk values the gold according to its weight, purity, current market price, condition and likely resale value. We then make a loan offer based on that assessment.

No. We lend against the precious metal only, so diamonds and other precious stones are not included in the valuation.

We can consider different purities, including 9ct, 14ct, 18ct, 22ct and 24ct gold. The higher the purity and gold content, the higher the underlying metal value is likely to be. Every item is tested before an offer is made.

Yes. Items pledged to Loan Against Assets.co.uk are securely stored for the duration of the agreement and covered under our relevant insurance arrangements. You will also receive documentation identifying the items held against your loan.

Normally, no. The loan is secured against the gold or jewellery, so we do not generally require payslips or a guarantor. We will require identification and may request proof of address, proof of ownership or further information for compliance purposes.

Many straightforward gold and jewellery loans can be completed on the same day. Once the item has been tested, valued and the required checks have been completed, the money can be paid using the agreed payment method.

No. Your jewellery will not be auctioned immediately after a missed payment. Contact Loan Against Assets.co.uk as soon as possible, as it may be possible to discuss an extension or renewal. If the agreement expires and remains unpaid, the item may eventually be sold in accordance with the agreement and the legal notice requirements.

Depending on the agreement, you may be able to repay the loan and interest in one payment, make interest payments during the term or apply to extend the agreement. The exact options, interest and repayment date will be explained before you proceed.

Yes. You can ask Loan Against Assets.co.uk for an early-redemption figure at any time. Any interest or charges payable will be calculated in accordance with the agreement you signed.

FAQs About Loans Against Stocks, Shares and ETFs

Answers regarding our loans against stocks, shares and ETFs.

Our main consideration is the value, liquidity and ownership of the investments being offered as security. A conventional credit score is not usually the main basis of the decision. Identity, ownership, anti-money-laundering and other necessary checks will still be completed.

This depends on how the security arrangement is structured and where the shares are held. In some arrangements, you remain the beneficial owner and continue to receive dividends. Voting rights and other benefits may be restricted. Loan Against Assets.co.uk will explain the position before the facility is completed.

If the value of the pledged investments falls below the agreed security level, you may be asked to provide more collateral or repay part of the loan. If the position is not corrected, some or all of the investments may have to be sold. The relevant valuation levels will be stated in the agreement.

Loan Against Assets.co.uk can consider quoted shares, funds and ETFs, subject to assessment. Large, liquid investments are generally easier to accept than unlisted, thinly traded or highly volatile shares. We will review the portfolio before confirming how much can be lent.

Not normally without prior agreement. The pledged investments are securing the loan, so selling or transferring them could reduce the available security. It may be possible to release or replace particular investments if enough collateral remains.

This depends on whether the arrangement is a fixed loan or a drawdown facility. With a fixed loan, interest normally applies to the amount advanced. With a credit facility, interest may apply only to the money actually drawn. Loan Against Assets.co.uk will provide the full cost before completion.

A lien or charge gives the lender security over the investments. While it remains in place, you may be unable to sell, transfer or withdraw the pledged assets without consent. The restriction is removed once the secured balance and applicable charges have been paid.

Borrowing can provide access to cash without immediately selling the portfolio. This means you may remain exposed to future dividends and price movements. Selling shares can create a Capital Gains Tax liability, whereas taking out a loan does not normally create a taxable gain by itself. A later sale or enforcement of the security could have tax consequences.

FAQ's About Loans Against Crypto (Bitcoin)

Answers regarding our loans against crypto (Bitcoin).

Potentially, yes. Loan Against Assets.co.uk can assess cryptocurrency as collateral, allowing you to access funds without making an immediate market sale. The crypto must be verified and placed under an agreed form of control or secure custody for the duration of the loan.

A centralised loan is arranged through a company that verifies the customer, holds or controls the collateral and issues the loan. A decentralised loan operates through blockchain-based smart contracts. Loan Against Assets.co.uk provides a direct asset-backed arrangement with clearly documented terms rather than requiring customers to navigate an anonymous DeFi protocol.

Because cryptocurrency can move sharply, the agreement will include an agreed loan-to-value level. If the value falls too far, you may be asked to provide more collateral or repay part of the loan. If you do not act and the liquidation level is reached, some or all of the crypto may need to be sold.

Every crypto-backed loan carries market, custody and counterparty risk. Before proceeding, Loan Against Assets.co.uk will explain how the crypto is held, who controls it and when it could be sold. Customers should never transfer cryptocurrency to an unverified wallet or provider.

Our decision is primarily based on the type, value and quantity of cryptocurrency being provided as collateral. Traditional credit scoring is not normally the main consideration. Identity, wallet ownership, source-of-funds and compliance checks will still be required.

There is no single maximum for every asset. The available LTV depends on the cryptocurrency, market liquidity and volatility. Bitcoin and Ethereum may support a different lending level from smaller or less liquid tokens. A lower LTV provides more protection against sudden price movements.

Interest will continue to accrue in accordance with the agreement, which can increase the LTV. If the agreed repayment or collateral conditions are breached, you may be asked to reduce the balance or provide more crypto. The collateral could ultimately be sold if the position is not corrected.

FAQs About Loans Against Probate and Inheritance Advances

Answers regarding our loans against probate and inheritance.

An inheritance advance normally provides money against part of an expected inheritance, with repayment made from the estate distribution. An inheritance loan creates a debt secured against the expected proceeds. Loan Against Assets.co.uk will clearly explain whether an arrangement is recourse or non-recourse and how the repayment is calculated.

Not necessarily. Depending on the arrangement, the agreed return may be paid from the inheritance when the estate is distributed. Other facilities may require monthly interest. The payment structure and total cost will be set out before you agree to anything.

This depends on the terms agreed at the beginning. The cost may be fixed, capped or calculated according to the length of time the money remains outstanding. Loan Against Assets.co.uk will explain whether the repayment amount can increase if probate takes longer than expected.

That depends on whether the agreement is recourse or non-recourse. Under a non-recourse arrangement, repayment is generally limited to the assigned inheritance. A recourse loan may leave the borrower personally responsible for a shortfall. This will be made clear in the agreement.

This may be possible where the executor has the necessary authority and the arrangement is in the estate’s interests. Loan Against Assets.co.uk will need to examine the will, probate position, estate assets, liabilities and the executor’s legal authority. Independent legal advice may also be required.

Where funding is based on the value of an inheritance, the estate and the applicant’s entitlement are normally more important than their personal credit score. Whether any credit search is required will depend on the particular structure and will be confirmed before an application proceeds.

We may require the will, identification, executor or administrator details, an estate valuation, details of debts and taxes, and evidence of the applicant’s expected entitlement. Some cases can be considered before probate is granted, while others will need to wait until the legal position is formally established.

An advance against your individual inheritance should not change another beneficiary’s legal entitlement. The executor will need to recognise the arrangement when distributing the estate, so all documents must be completed correctly. An advance against the estate itself may require wider approval and additional legal work.

Loans Against Assets

What Other Assets Can I Borrow Against?

We leverage the intrinsic value of your high-end assets to provide immediate liquidity. Click to learn more about our specific lending criteria.
Expansive aerial landscape of green and brown agricultural fields under a clear blue sky.
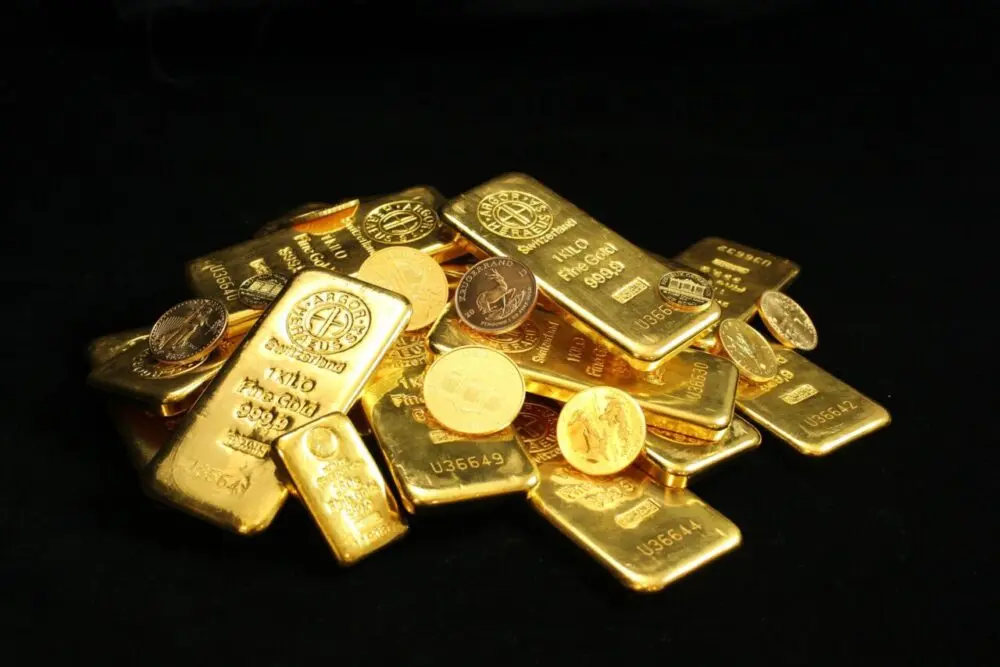
Close-up of shiny goldbars and coins - Loans against Gold
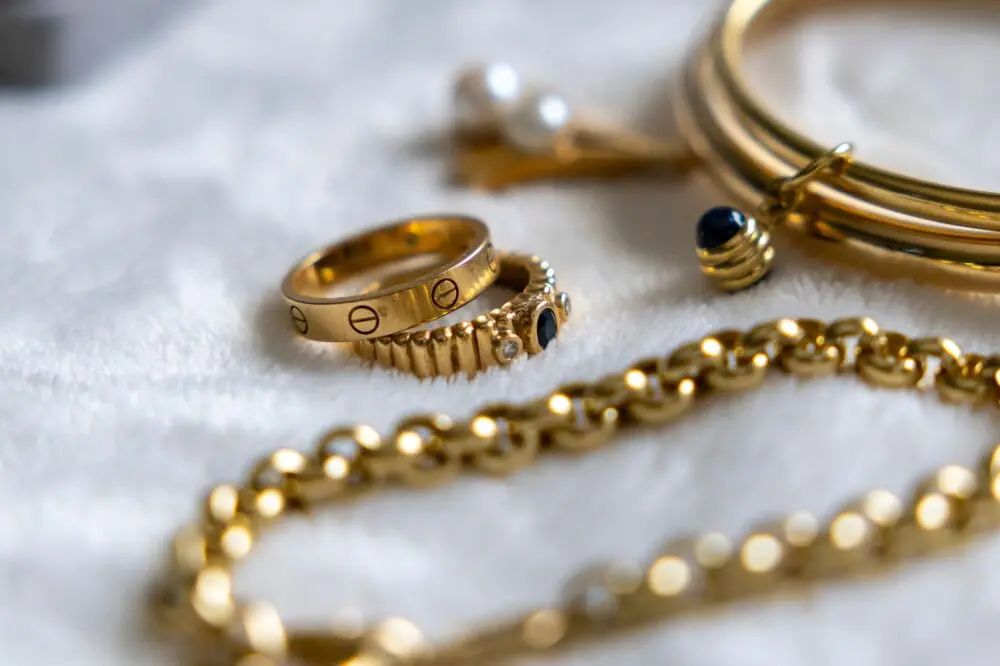
loans against jewellery Collection of gold rings, bracelets, and chains
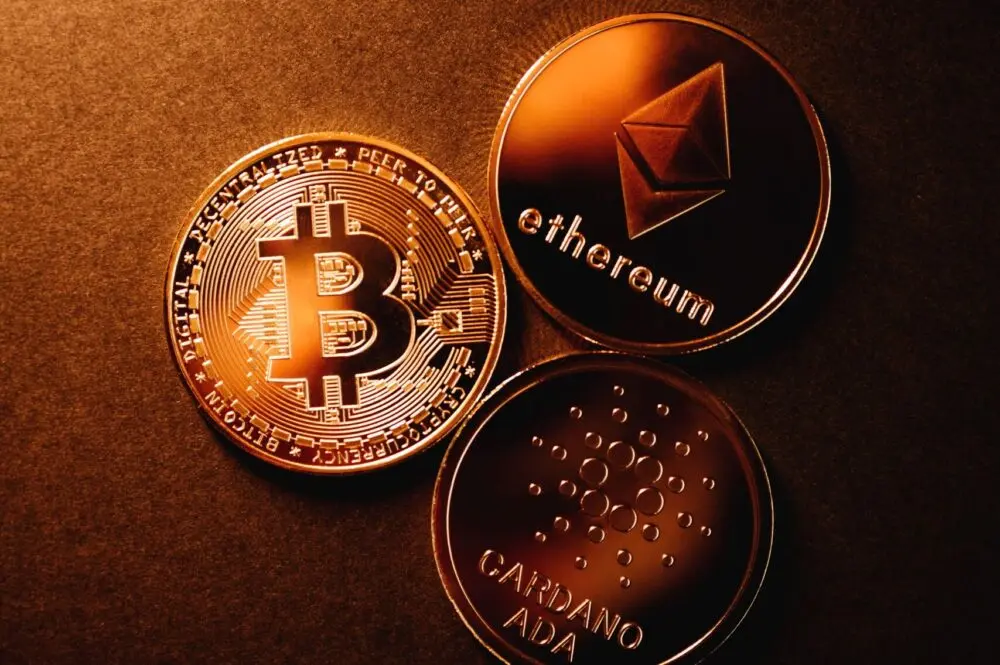
loan against crypto. Close-up of Bitcoin, Ethereum, and Cardano coins
loans against inheritance. mother handing child wooden home
loans against stock. Close-up of stock market chart showing trends and data on a digital screen.

May also accept other assets. Enquire directly.

Ready to find out what your asset is worth?

Request your free valuation now. Fill out the form or call us and we’ll get back to you the same day.